Family Budget in 2026: How to Handle Rising Grocery Costs
When grocery prices rise, an old household budget can stop matching reality. A practical family budget gives you a way to compare current income with housing, utilities, transportation, groceries, debt payments, savings, and other spending—and then adjust the categories putting the most pressure on your cash flow.
Quick Summary
- Update your family budget with recent spending instead of relying on old estimates.
- Give groceries a specific place in the budget and connect your grocery list to planned meals.
- Use a budget calculator to see the full household picture before making cuts.
- Review the budget regularly so one expensive grocery trip does not become a recurring problem.
What Is a Family Budget?
A family budget is a plan for how a household will use its income across essential expenses, discretionary spending, debt payments, and savings. It is not a fixed rule for how much every family should spend. Your numbers depend on income, household size, location, debt, housing costs, transportation, health expenses, and other circumstances.
The useful part is the process: record what comes in, track what goes out, compare actual spending with your plan, and make adjustments when the numbers change.
Why Inflation Can Make an Old Family Budget Stop Working
Inflation does not require every price to rise at the same rate. What matters for a household is that the cost of its particular basket of goods and services can change over time.
As of August 2026, U.S. Bureau of Labor Statistics data showed food prices were 2.7% higher than a year earlier, while food-at-home prices were 2.2% higher. Some categories moved differently. For example, fruits and vegetables were up 3.2% over the year, while nonalcoholic beverages were up 3.7%.
The USDA’s August 2026 Food Price Outlook forecast food-at-home prices to increase 2.5% during 2026, with a forecast range of 1.7% to 3.3%. A forecast is not a promise, and individual foods can move in different directions.
That is why a family budget built around last year’s grocery bill can become less useful. Instead of assuming that an old number is still appropriate, use recent receipts and bills to establish a new baseline.
How to Rebuild Your Family Budget With Real Numbers
Start with actual household numbers from the last two or three months. The goal is not to create a perfect forecast; it is to replace guesses with evidence.
1. List Your Take-Home Income
Use the amount that actually reaches your household after taxes and other payroll deductions. If income varies, use a conservative average based on recent months.
2. Separate Fixed and Variable Expenses
Fixed expenses may include rent or a mortgage, insurance, debt payments, and other recurring bills. Variable expenses can include groceries, fuel, utilities, household purchases, and discretionary spending.
3. Find the Categories Creating the Biggest Gap
Compare your planned amounts with actual spending. If groceries are consistently above the amount in your budget, determine whether the cause is higher prices, household changes, food waste, impulse purchases, or simply an unrealistic starting number.
4. Adjust the Plan Instead of Hiding the Problem
A budget is useful when it reflects reality. If one category needs more money, identify where that money can come from without creating a larger problem elsewhere. That may mean reducing discretionary spending, changing a recurring expense, increasing income, or revisiting savings and debt priorities.
For a broader household view, use The Penny Flow budget calculator to organize income and expenses in one place.
Family Budget Example
The following is a hypothetical example, not a recommended spending formula.
- Take-home income: $6,000 per month
- Housing and utilities: $2,100
- Transportation: $700
- Insurance and health costs: $500
- Groceries: $750
- Debt payments: $500
- Savings: $600
- Other spending: $550
- Remaining monthly buffer: $300
The important lesson is not the dollar amount assigned to each category. It is that the household can see how groceries fit into the entire budget. If groceries rise from $750 to $850, the family can identify the $100 change and decide what adjustment makes sense instead of discovering the problem only after the money is gone.
How to Set a Grocery Budget for Your Family
There is no universal grocery percentage that fits every family. Household size, age, location, dietary needs, income, food preferences, and prices all matter.
A better starting point is your own recent spending. Add your grocery receipts from the last several weeks, calculate the average, and compare that amount with your total household budget. Then decide whether the current level is sustainable.
USDA food-price data can provide useful context for changes in the broader market, but national price indexes are not a substitute for your household’s actual receipts.
Build Your Grocery List From Your Family Budget
A grocery list works better when it is connected to a spending limit and a meal plan. Start by checking what you already have, decide which meals you expect to prepare, and then build the list from those meals.
- Check your pantry and refrigerator. Use what you already own before buying duplicates.
- Choose several meals. Include meals that use overlapping ingredients when practical.
- Create one shopping list. Keep the list tied to the meals and household needs.
- Compare unit prices. Package size and brand can make the apparent bargain misleading.
- Review the receipt. After shopping, compare the actual total with the amount you planned to spend.
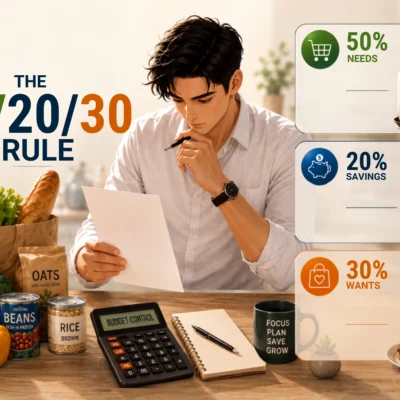
For a more detailed grocery-focused approach, see The Penny Flow guide to grocery shopping, shopping lists, and the 50/20/30 rule.
How to Control Overspending Without Cutting Everything
Overspending is easier to address when you identify what is actually causing it. A grocery bill that is higher than planned does not automatically mean you bought unnecessary items.
Ask four questions:
- Did prices increase?
- Did we buy more because of a special event or household change?
- Did impulse purchases or convenience foods increase the total?
- Did we underestimate the amount needed for the household?
The answer determines the response. If prices are higher, update the budget. If impulse purchases are the issue, strengthen the shopping-list process. If the household’s needs changed, revise the plan. If food waste is significant, buy smaller quantities or plan meals around ingredients you already have.
What to Do When You Break Your Grocery Budget
One expensive shopping trip does not mean your entire budget has failed. First, record the actual amount. Then identify why the total was higher and decide whether the next week’s plan needs a small adjustment.
- Planned: $175
- Actual: $205
- Difference: $30 over plan
- Question: Was the $30 caused by higher prices, a necessary purchase, or avoidable spending?
This approach turns a budget overrun into information. Repeated overruns may indicate that the original grocery target needs to be changed or that another spending habit needs attention.
Should You Use a Family Budget Calculator?
A budget calculator can be useful when you need to see several categories together. It can help you compare income with expenses, estimate remaining cash flow, and identify where a change in one category affects the rest of the household plan.
The calculator does not decide what your family should spend. Your actual bills, priorities, and circumstances do that. Use the tool to organize the numbers and make the trade-offs visible.
For Penny Flow readers, the budget calculator is a practical starting point for entering your own figures.
A Simple Weekly Family Budget Review
You do not need to rebuild your entire budget after every grocery trip. A short weekly review can keep small differences from becoming large surprises.
- Check your current account balances.
- Record major spending from the previous week.
- Compare grocery spending with your grocery plan.
- Note any unusual expenses coming in the next week.
- Make one small adjustment if needed.
During periods of changing prices, a monthly full-budget review can complement these shorter weekly checks. The purpose is to keep the budget connected to actual household behavior.
Actionable Steps to Start This Week
- Collect your recent receipts. Calculate your actual weekly grocery average.
- Update your family budget. Replace old estimates with current income and expense numbers.
- Choose a grocery target. Make it realistic for your household rather than copying a universal percentage.
- Plan several meals. Build your shopping list around those meals and what you already have.
- Review the receipt after shopping. Look for patterns instead of judging one purchase.
- Repeat the review. Adjust the budget when the underlying numbers change.
Frequently Asked Questions
Why are grocery prices still high in 2026?
U.S. food prices remain above their year-earlier levels. In August 2026, BLS reported that food-at-home prices were 2.2% higher than in August 2025. Different food categories moved at different rates, so your household experience can differ from the national average.
Will grocery prices come down?
Prices can rise more slowly without returning to earlier levels. USDA’s August 2026 outlook forecast food-at-home prices to increase 2.5% during 2026. That is a forecast, not a guarantee, and individual categories can move differently.
How much of my family budget should go to groceries?
There is no universal percentage that fits every household. Start with your recent grocery spending, compare it with your take-home income and other essential costs, and adjust based on your household’s needs and priorities.
What is the fastest way to reduce grocery overspending?
Start by planning meals, shopping from a specific list, checking what you already have, and reviewing the receipt afterward. These steps can reduce avoidable purchases, although the savings will vary by household.
Should I use a budget calculator or a spreadsheet?
Either can work. The important thing is that your tool lets you record actual income and expenses and compare them with your plan. A calculator can be convenient for organizing the numbers; a spreadsheet may offer more customization.
How often should I review my family budget?
A short weekly spending review can help you catch changes early, while a more complete monthly review can help you update categories and priorities. Review more often when your income or major expenses change.
Does food insecurity mean a family is simply overspending?
No. Food insecurity is a broader measure of difficulty obtaining enough food because of limited resources. USDA reported that 13.7% of U.S. households were food insecure at some point during 2024. That statistic should not be interpreted as evidence that those households simply failed to budget.
The Bottom Line
A useful family budget is not a promise that prices will stay fixed. It is a system for responding when they do not.
Start with real household numbers. Give groceries a realistic place in the overall plan. Connect your shopping list to meals and actual needs. Review overspending without automatically treating it as a personal failure. Then adjust the budget when the underlying numbers change.
Inflation is measured at the economy-wide level, but your budget is personal. The most useful number for your family is the number you can support with your own income, bills, receipts, and priorities.
Sources
- U.S. Department of Agriculture, Economic Research Service — Food Price Outlook, August 2026
- U.S. Bureau of Labor Statistics — Consumer Price Index, August 2026
- U.S. Department of Agriculture, Economic Research Service — Household Food Security in the United States in 2024
- Consumer.gov — Making a Budget
- Consumer Financial Protection Bureau — Analyzing Budgets
Author: Abdullah Riaz | Last updated: September 22, 2026
This article provides general educational information and is not individualized financial advice.